By: Dr. Tamara Patzer
October 12, 2026
In brief: A plan that cannot change eventually stops fitting the family it was meant to serve. A New Orleans tax attorney explains why flexibility must be built into family wealth plans, with scheduled adjustment points and clear authority to change course, using his book’s warnings about rigidity and current California and IRS figures.
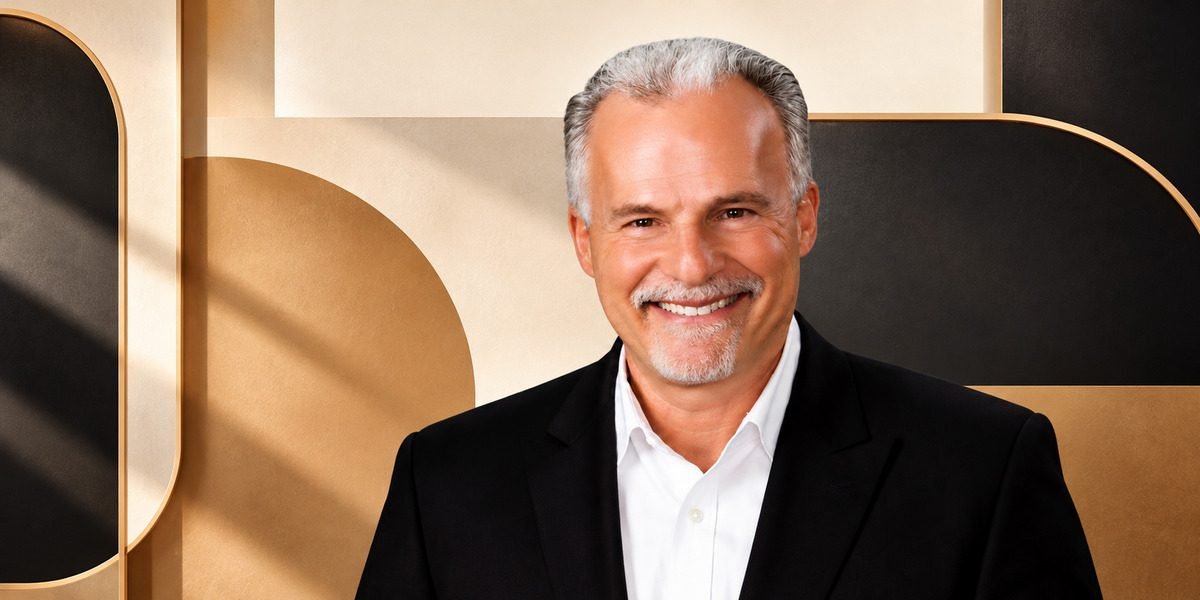
A plan written in a good year can look foolish in a bad one. A trust drafted for one family structure can pinch when a child marries, a business is sold or a tax rule shifts. The plan did not fail because it was badly drafted. It failed because it assumed the world would hold still. Todd M. Villarrubia, a New Orleans attorney who focuses on tax and estate planning, wrote Entrepreneurial B.E.A.S.T. Mode™ with that risk in mind. His warning is short: “Rigidity can destroy generational wealth; you must be able to adapt and react quickly.”
What Makes a Plan Rigid?
Three things, mostly. The first is documents that fix decisions without saying who may revisit them. The second is advisers who see their work as finished once it is signed. The third is a family that avoids talking about the plan because the topic is uncomfortable. Any of the three can freeze a plan in place long after circumstances have moved on.
California families with complex financial circumstances may have particular reasons to review their plans. SmartAsset’s 2026 estimate, based on IRS data and tax filers rather than households, places the estimated adjusted gross income threshold for the top 1% in California at $987,325. That figure is an income threshold, not a measure of wealth, but it illustrates why families with substantial income and varied assets may need to revisit the assumptions built into their plans.
What Does the Book Say About Discipline?
That adaptability does not mean impulsiveness. The author draws a contrast: “The common thread among them all isn’t greed but discipline.” A family that adapts well does so by following a routine, not by reacting to each new headline. Discipline here means a calendar of check-ins, a clear process for changes and a habit of writing down why decisions were made.
The routine is what makes flexibility safe. A plan that can change at the whim of one person is as dangerous as one that cannot change at all. The goal is a plan that can change through a defined process, with the right people involved.
What Are Adjustment Points?
Dates or events at which the family and the advisers formally ask whether the plan still fits. Some are calendar-based: once a year, every three years, whenever a child turns a certain age. Some are triggered by events: a sale, a birth, a death, a move, a change in tax law, a new business. At each point, the question is the same: what has changed, and does the plan need to?
Writing the adjustment points into the plan is more than a formality. It gives everyone permission to raise concerns, and it prevents the plan from turning into an object that nobody dares to touch.
Who Has Authority to Change the Plan?
This is the question most plans leave unanswered. A trust may name a trustee and a protector, an agreement may give a manager certain powers and a family charter may describe a council. But in many families nobody can say who decides whether a change is needed, who proposes it and who approves it.
The author stresses that coordination should be built into the arrangement: “The real power lies not in individual strategies, but in their coordinated application.” A group that has authority, meets regularly and has the full set of facts can adjust the plan intelligently. A group that meets only in crises cannot.
How Do Tax Rules Fit in?
They change on their own schedule, which is a reason for the plan to be revisited. The IRS lists $15,000,000 per person as the federal basic exclusion amount for people who die in 20262. That amount is established under federal law and can change in future years. A family whose plan relies on an older figure should ask an attorney whether its assumptions still apply.
State rules also shift, and a plan drafted for one set of facts may not fit another. Rather than predicting changes, the better habit is to schedule time to look for them.
What Does the Family Data Suggest?
That wealth changes unevenly across the distribution. The Federal Reserve’s newest family finances release, issued October 9, 2026, puts 2025 median family net worth at $215,900, up 2% in real terms from 2022, and mean net worth at $1.24 million, up 7%. These figures describe the distribution of family wealth rather than the circumstances of any particular family, reinforcing the value of reviewing a plan as personal circumstances change.
How Should a Family Build Flexibility?
In five steps.
● Write down the purpose of the plan, so changes can be judged against it.
● List the adjustment points, both dates and events.
● Name who can propose a change and who must approve it.
● Keep a record of every change and the reason for it.
● Meet with all advisers at each adjustment point, not just the one who drafted the document.
Done well, these steps create a defined process for reviewing the plan and keeping its assumptions current.
What Mistakes Do Families Make?
Treating a signed document as final. Letting the advisers who drafted it assume that nothing needs to change. Avoiding adjustments because they might expose disagreements. Making changes in private, without telling the people affected. Each of these makes the plan brittle. Openness and a process are the antidotes.
What Can a California Family Do This Quarter?
Find the plan, in whatever form it exists. Write a paragraph about what has changed since it was drafted. Bring that paragraph to the next meeting with your attorney and ask whether any piece needs attention. Put the next adjustment point on the calendar before leaving the room.
Common Questions
Does flexibility mean the plan is unreliable? No. A plan with a defined process for review and change can be easier to maintain as circumstances evolve.
How often should a plan be revisited? At least yearly and after major events. An attorney can suggest a schedule.
Can I make changes myself? Some can be made informally, but many require legal documents. Seek legal advice before changing anything that is already signed.
Sources
1. SmartAsset, Income Needed to Be in the Top 1% in Every State (2026)
2. Internal Revenue Service, What’s New: Estate and Gift Tax
3. Federal Reserve Board, press release on the 2025 Survey of Consumer Finances
About the author. Dr. Tamara Patzer is a publisher and former newspaper editor. She was on the staff of The Charlotte Sun when it was named a 2005 Pulitzer Prize finalist for its Hurricane Charley coverage.
About the source. Todd M. Villarrubia is an attorney with an LL.M. in Taxation and a Juris Doctorate. He is an Accredited Estate Planner, a Board Certified Expert in Estate Planning and Administration, and a Fiduciary Investment Advisor Representative. He is the author of Entrepreneurial B.E.A.S.T. Mode™. Wealth Planning Law Group, 101 W. Robert E. Lee Blvd., Ste 404, New Orleans, LA 70124. Phone: 504-982-8207; email: todd@lawealthplan.com; website: Wealth Planning Law Group.
Disclaimer: Attorney advertising. Sponsored feature written on behalf of Todd M. Villarrubia. This article is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Results vary.